You can avoid Colombia’s tax on worldwide income and wealth by staying a tax non-resident — meaning you spend no more than 183 days in the country during any rolling 12-month period.
In short
- You become a Colombian tax resident after more than 183 days within any rolling 12-month period, not a calendar year.
- A resident is taxed on their entire worldwide income on a progressive scale up to 39%, with the first roughly $14,000 tax-free.
- A separate worldwide wealth tax, the Impuesto al Patrimonio, applies — its entry threshold was recently lowered, and rates start at 0.5%.
- Colombia has no double taxation treaty with Germany or Austria, so the tie-breaker rule doesn’t apply.
- Living in Medellín 4–5 months a year lets you stay under the 183-day threshold and avoid full taxation.
The 183-Day Rule: When Colombian Tax Residency Kicks In
Colombian tax residency status begins once someone spends more than 183 days in the country within any 12-month period. That period isn’t tied to the calendar year — it’s a rolling window: the system looks at any 12 consecutive months, not fixed January-to-December boundaries.
The days don’t need to be consecutive — what counts is the total number of days present in the country during that window. The type of visa makes no difference: a digital nomad visa, a residence permit, or any other status doesn’t change how the days are counted. What matters is physical presence on Colombian territory.
The threshold cuts both ways. Someone who stays under the 183-day line is not considered a resident and pays tax only on Colombian-source income. Someone who crosses that line becomes a resident, and from that point their entire worldwide income and wealth become taxable, subject to specific exceptions that may arise from a double taxation treaty. This rule is described as a fairly hard line, with no formal in-between status — though the details of how it applies are worth confirming for a specific situation.
This rule is described as a fairly hard line, with no formal in-between status — though the details of how it applies are worth confirming for a specific situation.
Residency begins once you spend more than 183 days in the country across any 12 consecutive months, not the calendar year. Visa type doesn’t matter — only actual presence counts.
What a Colombian Resident Pays: Income Tax and Wealth Tax
Once someone crosses the 183-day threshold, they fall under Colombian tax on their entire worldwide income — on a progressive scale up to 39%. The first roughly $14,000 of income is tax-free; everything above that is taxed at increasing rates.
The second layer of the burden isn’t about income at all — it’s about wealth. Colombia has a separate wealth tax, the Impuesto al Patrimonio, and a resident must include their entire net worldwide wealth in the calculation, not just Colombian assets.
The entry threshold for this tax was recently lowered by an emergency decree; figures cited vary, ranging from roughly 2 to 3.6 billion Colombian pesos (that is, roughly $500,000 to $900,000). The exact current threshold is worth confirming right before filing, since these parameters change periodically. Rates start at 0.5% and climb to noticeably higher levels at the top end. Because the threshold was lowered, the tax now reaches far beyond the ultra-wealthy to a much broader group of residents with assets.
On top of that, residents also have an annual obligation to declare foreign assets — disclosing overseas holdings to the tax authority.
Key Colombian Tax Thresholds for Residents
The core figures that determine a Colombian resident’s tax burden.
- Residency threshold183 days per 12 months
- Tax-free incomeabout $14,000progressive scale above that
- Top income tax rateup to 39%
- Lowest wealth tax ratefrom 0.5%noticeably higher at the top end
A resident must include their entire net worldwide wealth in the wealth tax calculation, not just Colombian assets. The entry threshold was recently lowered, and the tax now reaches a much broader group of people.
Double Taxation Treaties: Why Germany and Austria Are Out of Luck
There is no comprehensive double taxation treaty between Germany and Colombia. Colombia has such treaties with Spain, Switzerland, Chile, Canada, Mexico, and a number of other countries — but not with Germany, and not with Austria.
The difference is significant specifically for people from German-speaking countries: given the same move to Colombia, a Swiss citizen ends up in a different tax situation than a German or Austrian citizen — purely because a treaty between the two countries exists or doesn’t.
In practice, the absence of a treaty means there’s no tie-breaker rule to fall back on — the mechanism that, in disputed cases, helps determine a single country of tax residency. Without it, the risk is becoming a tax resident of two countries at once and paying twice — which makes correctly exiting the tax residency of one’s home country a mandatory condition, not a formality.
the risk is becoming a tax resident of two countries at once and paying twice
Colombia has no comprehensive double taxation treaty with Germany or Austria, so the tie-breaker rule that determines a single country of residency doesn’t apply.
Correctly Exiting Your Home Country: A Mandatory Condition
Without a double taxation treaty, the tie-breaker rule doesn’t apply — meaning that if statuses conflict, your home tax authority isn’t obligated to yield to Colombia. The only protection in this situation is a clean, fully correct exit from your home country: without it, changing tax residency in Colombia guarantees nothing on its own.
In practice, there have been cases where the move to Medellín went smoothly, both in feel and in timing, but the exit from the home country was handled carelessly — and as a result, the person unexpectedly ended up subject to Colombian tax on their entire worldwide income. The legal situation in Colombia remains unstable and keeps changing, which raises the cost of a mistake even further precisely where there’s no treaty with Germany to close the double taxation gap.
the move to Medellín went smoothly, both in feel and in timing, but the exit from the home country was handled carelessly — and as a result, the person unexpectedly ended up subject to Colombian tax on their entire worldwide income
Medellín as a Part-Time Base: Living Under the 183-Day Threshold
In practice, some foreigners use Colombia as a base for part of the year: they live in Medellín for 4–5 months, stay cleanly under the 183-day threshold, and don’t fall under the tax on worldwide income and wealth. This approach requires precise day-counting within the rolling window — that count alone determines whether someone ends up with full residency or a part-time base.
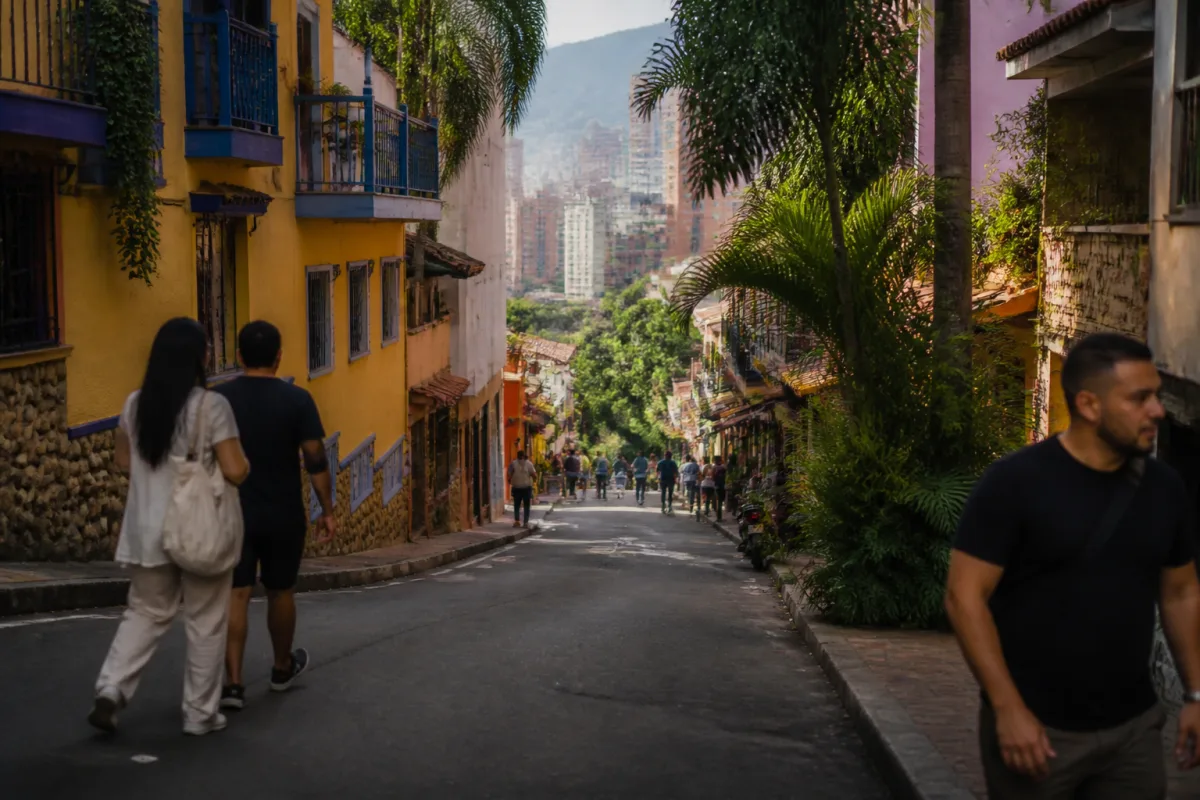
The recommended location for this strategy is Medellín, in the Antioquia region, near the coffee-growing zone. The city holds a spring-like climate year-round, hence the nickname “the city of eternal spring.” Neighborhoods like Poblado or Laureles have a large international community, and a comfortable life there runs $1,800–$2,800 a month.
The risk in this strategy isn’t the rule itself — it’s breaking it through inattention: there have been cases of people who moved to Medellín out of love for the city and accidentally exceeded the threshold, landing under Colombia’s worldwide wealth tax. Anyone who wants to live in the country year-round needs to consciously accept full taxation of worldwide income and wealth ahead of time — or run the numbers precisely before moving.
Staying under the 183-day threshold and avoiding tax on worldwide income and wealth requires precisely tracking days present within the rolling 12-month window.
Frequently asked questions
What happens if someone accidentally exceeds the 183-day threshold while already in Colombia — can anything be fixed after the fact?
The rule itself is strict: exceeding the threshold automatically makes someone a tax resident for the whole period, and this isn’t reversed retroactively. The only thing left to do is correctly exit tax residency in your home country, so you don’t end up paying tax in two places at once.
What happens if a German citizen becomes a Colombian tax resident but doesn’t properly exit the German tax system?
Without a double taxation treaty between Germany and Colombia, the tie-breaker rule doesn’t apply, so the German tax authority isn’t required to automatically cede sole residency status to Colombia. In that situation, the risk is being taxed in both countries at once.
Does a Colombian resident need to file a separate declaration for foreign assets, on top of the income tax return?
Yes, residents have a separate annual obligation to declare foreign assets — disclosing overseas holdings to the tax authority. This is on top of calculating income tax and wealth tax.
Does Colombia have a double taxation treaty with the United States?
There’s no information indicating Colombia has such a treaty with the United States — among the countries named as having treaties with Colombia are Spain, Switzerland, Chile, Canada, and Mexico.
If someone splits the year between Medellín and another Colombian city, do the days still add up toward the overall 183-day threshold?
The rule counts actual presence on Colombian territory as a whole, not tied to a specific city, so days spent in any region of the country add up toward the overall 183-day count.

Comments
Reader experience is useful, but it is not advice: check the rules on the official site.
No account needed: click Sign in, type any name, and you are done.